Happy People Pay Happy Prices?

If happy people pay happy prices, then what prices pay under-invested and under-performing asset managers? I will tell you what price – any price. If the rally in January was born out of an outside catalyst (less bad than expected new taxes), the rally in May has been led by pure momentum and fear of missing out, where managing career risk has gradually become more important than managing market risk.

Every couple weeks or so, bears show up and boldly try to call a top, acting like we don’t remember the last time they made the same call. You saw the ton of posts on the potential QE tapering last weekend and the potential negative consequences for equities. Guess what, there is no difference between being early and being wrong, depending on your time-frame of course. If your timeframe is eternity and you don’t take into account opportunity costs, then eventually you will be right, if this is what is important to you. I rather make money.

There are two type of markets – trending and range-bound and they come after each other in an endless cycle. Our job is not to complain about divergences and to ponder on the potential impact of central banks’ monetary policies. Our job is to take full advantage of healthy market and to manage risk.

All stocks that consolidated sideways for the past two to four weeks, are breaking out, one after another. This is what happens in trending markets. Price momentum is the catalyst. The fear of missing out trumps the fear of losing. They say that happy people pay happy prices, but bull markets persist because people don’t believe in them. Bull markets climb the proverbial wall of worry. People say that they don’t want to chase and yet corrections last a couple hours. The slightest dips are getting bought.

A bull market will bail you out and it will forgive your mistakes, but if you really want to outperform, you either have to pay attention to sector rotation or have the discipline to stick with your winners long enough to make a difference. When there are so many good looking technical setups out there, it is enticing to jump from stock to stock and chase after multiple small percentage gains, but looking back you will realize that this is not the wisest approach.

Refiners ($TSO, $CVI, $PSX…) and oil & gas svs ($FTI, $COG…) stocks started breaking out on Friday. Many of them are still close to their bases and it seems like the next beneficiary of an ongoing sector rotation, so you might want to pay attention to this sector. The success rate of breakouts will depend a lot on the price action in crude oil.

It is absolutely amazing how energy and basic material stocks could stay near multi-year highs given the strong price action in the U.S. Dollar. Other cyclicals have also been extremely strong – financials, homebuilders, industrials, even semi-conductors under the surface.

Short squeezes continue with full force and happen even in stocks with questionable fundamentals. In fact, big short squeezes always happen in stocks with questionable fundamentals. Their short interest would not be high, if everything was dandy there. I guess this is one of the reasons why two of the most controversial industries of the past few years, have been leading in the past month or so – solar and education stocks.

Large ticket stocks like $PCLN, $CRM and $GOOG are charging higher and for a good reason – the fastest way to gain market exposure is via high-liquid, high ticket momentum stocks.

There is always something to worry about. Yes, it is getting a little frothy out there with recent IPOs running wild. By no means, it is “1999-kind of” wild. Actually, IPOs outperforming is a good sign of risk appetite.

The new all-time high list is super-diverse and the number of stocks making annual highs is at levels last seen in 2010. Usually extreme levels lead to some form of mean-reversion, but trends could continue longer than contrarians could remain solvent. And as we have talked multiple times on this site, sometimes being a contrarian means staying with the underlying trend.

This is a reprint of my St50 weekly market review. You could see my latest list here.
Tesla Motors Could Be A 100 Billion Dollar Company in 10 Years

Screen Shot 2013-05-09 at 8.27.57 PM

Here is how investing in growth stocks works.

The stock market is a forward-looking mechanism that discounts pro-actively, often 6 to 18 months into the future. Price momentum usually leads earnings and sales growth in the first phase of any long-term stock market trend. Then, if fundamentals don’t catch up, there’s a mean-reversion.

The market constantly discounts events and processes that haven’t happened yet. As a result, it will sometimes discount events that will never happen. With other words, sometimes is right, sometimes is wrong, but it is not stupid. It makes an assumption, sometimes based only on a good story, other times based on real fundamentals; it discounts that assumption pro-actively, but in the same time it is expecting positive feedback in terms of actual earnings and sales growth. If the latter don’t come, a correction follows. If earnings and sales growth numbers confirm and exceed market expectations, the trend continues.

In the case with Tesla, the stock had doubled in the six months preceding the announcement of it first profitable quarter. The market has been expecting and discounting that event. Apparently, a bull market and a large short float (40%) have contributed to the size of the move, but the story of Tesla is not too different than the story of many other high growth technology companies with innovative products. In 2003, Blackberries were the hottest phones on the market. Blackberry stock quadrupled in the 12 months leading to its profitable quarter. Then, in the next five years, it quadrupled a couple more times (that 16X for those who have missed math at school).

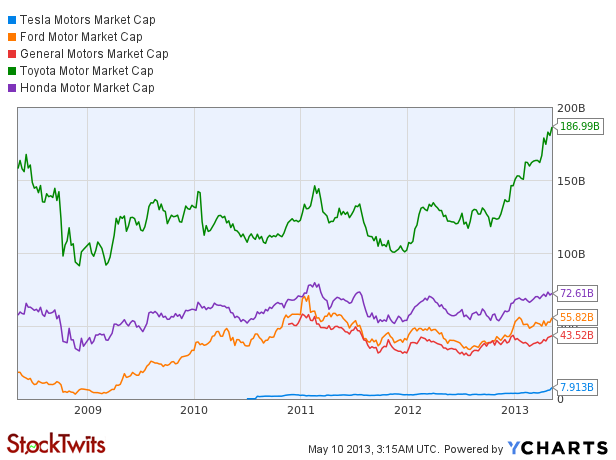
Here is a graph comparing the market caps of the major publicly traded car companies – Tesla Motors, Toyota, Honda, Ford and GM. The German Daimler (owns Mercedes and Chrysler) and BMW have each a market cap of about 50 Billion Euro. Volkswagen, which also makes Audi and Porsche, has a market cap of about 75 Billion Euros.

Screen Shot 2013-05-09 at 8.29.49 PM

Apparently, Tesla’s earnings and revenues are very far from its competitors’ numbers, but Tesla is a lot younger company. Every big tree starts as a small acorn. Blackberry was a $1 Billion dollar company in 2002. Then it became $80 Billion in 2007. Apple was a 5 Billion dollar company in the early 2000s.

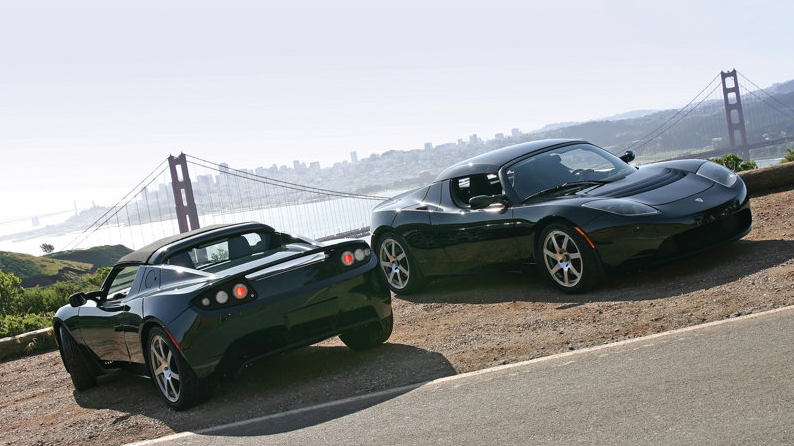
Elon Musk might not have the marketing genius and presentation skills of Steve Jobs, but he is a long-term thinker like Jeff Bezos. He has e detailed long-term plan of how Tesla is going to take over the world. First start with an expensive, high-margin sports model. Then gradually increase its scope by creating cheaper vehicles that could be afforded by a larger number of people. Tesla is not just an expensive toy for people with a lot of money. It is a freaken spaceship on wheels, which is technologically superior just like Apple’s products were 3-4 years ago. Consumer Reports just called them “the best car they have ever tested”. Most importantly, the early adopters love Tesla and talk about with with exclamation marks. The hardest group to please is loving Tesla. What they love today, many of us are likely to love 2-3 years from now.

If Elon’s plans work out, 10 years from now, Tesla’s market cap could easily be close to the big players of today as electric cars will be seen everywhere. What if in the future all cars are electric? Tesla is already licensing its superior technology to Daimler and Toyota.

Of course, there is always a chance that the company might turn out to be a flop. The market is currently giving Tesla the benefit of the doubt. It has discounted a bright future. Remember that the market is forward looking and myopic at the same time. It doesn’t discount too far into the future, and for a good reason. The further you go into the future, the higher the uncertainty. For a long-term price trend to be sustained, Tesla will need to deliver some serious earnings and sales growth. The good news for Tesla is that it has already made good money for a lot of its investors, which means that Elon Musk has earned their trust and patience, just like Jeff Bezos has done. This will give him more room to maneuver and experiment.

There will be the inevitable 40%-50% corrections along the way, but a $100 Billion market cap is achievable in the next 10 years. How many people do you think are going to ride the whole trend? If history is a good indicator, very few.

I WANT To Be The Slow Money

w

We live in fascinating times:

  • Warren Buffett is on Twitter. At least he tweeted once – “Warren is in the house”, probably trying to subtly remind us that he still likes housing stocks. 🙂 In 2008 he didn’t know how to listen to his voice machine and this is why Lehman went under. When all is said and done, he remains the best investor of all times. The Steve Jobs of Investing.
  • A few weeks ago, the Associated Press twitter account was hacked, which caused a mini flash crash in the world most liquid asset – the S & P futures. We don’t even remember that anymore. A few weeks is nine months in social web time.
  • News and rumors are breaking faster on the social web than on $2000 a month Bloomberg terminals. They are analyzed faster and with much deeper perspective on the social web too. No research shop could possibly compete with 30 independent analysts, who could devour any earnings or economic report in a matter of minutes. At least, it can’t compete on velocity.

The world is going faster. A lot faster. Does that mean that you have to become faster in order to survive and prosper. No! Velocity is not your forte in a world driven by high frequency algorithms that make several thousand trades in a second. Your only chance of survival is to become the slow money. To step back, look at the big picture, spot trends (catalysts) that are going to last for more than a few days and find a way to ride them.

Being The Slow Money doesn’t mean that you have to think like Warren Buffett. He likes to joke that he loves businesses that could be run by idiots, because sooner or later it will happen. He says the he hates uncertainty and wants to invest in companies that are likely to be still around 10 years from now and with higher earnings.

The truth is that no one knows how the world will look like 10 years from now. Maybe people will still eat Cheerios, maybe they won’t. Who knows. We might be all on customized nutrition pills by then. Investing in companies likely to be around 10 years from now is not a guarantee of success. We don’t know how their shares will perform in the meantime. There are no sure things in the market. What is widely perceived as being safe, could be very risky, especially if the consensus opinion is on your side.

Being the slow money means that you don’t have to obsess with every move in the markets and try to find an explanation behind it. Being ‘the slow money’ means that you don’t need to own 50 different positions and to chase after every breakout to make a few percents. Being ‘slow money’ also means that you might have to cut from your exposure to the fast web…