I WANT To Be The Slow Money

w

We live in fascinating times:

  • Warren Buffett is on Twitter. At least he tweeted once – “Warren is in the house”, probably trying to subtly remind us that he still likes housing stocks. 🙂 In 2008 he didn’t know how to listen to his voice machine and this is why Lehman went under. When all is said and done, he remains the best investor of all times. The Steve Jobs of Investing.
  • A few weeks ago, the Associated Press twitter account was hacked, which caused a mini flash crash in the world most liquid asset – the S & P futures. We don’t even remember that anymore. A few weeks is nine months in social web time.
  • News and rumors are breaking faster on the social web than on $2000 a month Bloomberg terminals. They are analyzed faster and with much deeper perspective on the social web too. No research shop could possibly compete with 30 independent analysts, who could devour any earnings or economic report in a matter of minutes. At least, it can’t compete on velocity.

The world is going faster. A lot faster. Does that mean that you have to become faster in order to survive and prosper. No! Velocity is not your forte in a world driven by high frequency algorithms that make several thousand trades in a second. Your only chance of survival is to become the slow money. To step back, look at the big picture, spot trends (catalysts) that are going to last for more than a few days and find a way to ride them.

Being The Slow Money doesn’t mean that you have to think like Warren Buffett. He likes to joke that he loves businesses that could be run by idiots, because sooner or later it will happen. He says the he hates uncertainty and wants to invest in companies that are likely to be still around 10 years from now and with higher earnings.

The truth is that no one knows how the world will look like 10 years from now. Maybe people will still eat Cheerios, maybe they won’t. Who knows. We might be all on customized nutrition pills by then. Investing in companies likely to be around 10 years from now is not a guarantee of success. We don’t know how their shares will perform in the meantime. There are no sure things in the market. What is widely perceived as being safe, could be very risky, especially if the consensus opinion is on your side.

Being the slow money means that you don’t have to obsess with every move in the markets and try to find an explanation behind it. Being ‘the slow money’ means that you don’t need to own 50 different positions and to chase after every breakout to make a few percents. Being ‘slow money’ also means that you might have to cut from your exposure to the fast web…
3D-Printing Stocks Are Setting Up Again

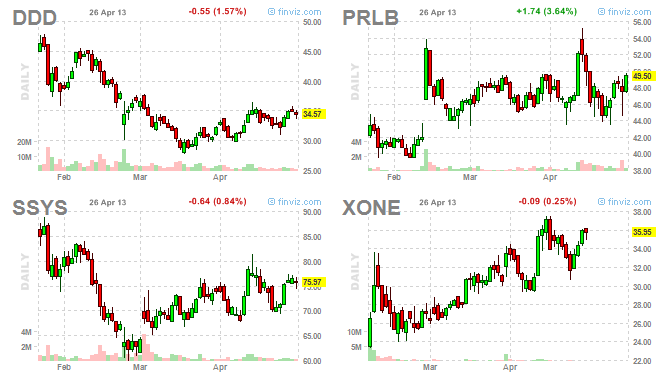
It is not a secret that 3D printing has been one of the most discussed industries in the past 6 months and one of the best performers in the past 12 months. There are currently four relatively liquid, publicly traded stocks that represent it: 3D Systems ($DDD), Stratasys ($SSYS), Proto Labs ($PRLB), The ExOne Company ($XONE) and it seems that they are all setting up for higher prices.

Screen Shot 2013-04-28 at 6.34.21 PM

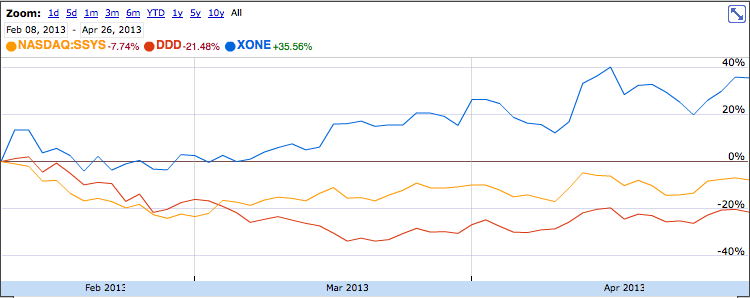
The two big ones $DDD and $SSYS took quite a beating after $XONE had its IPO on February 8th.

Screen Shot 2013-04-28 at 6.49.20 PM

There are two ways to look at an IPO in a hot industry:

1) It is positive. It shows that investment banks are confident in market’s ability to absorb the new supply. Stocks from the same industry that are already public often appreciate in anticipation of the new IPO.

2) Too much additional supply of shares is just like overbuilding capacity – it is not a positive in long-term perspective as it puts pressure on prices.

$XONE is a tiny company with current market cap of $500M. It is unlikely to be the major catalyst for the selloff in $DDD and $SSYS. The total market cap of the all publicly traded 3D printing industry is still relatively small for a small surge in supply to matter.

The main reason behind the pullbacks was probably earnings related and not living up to market’s expectations. Mr. Market constantly discounts evens that have not happened yet. As a result, it will often discount events that will not happen. This is not to say that it will remain blind-sighted forever. A good story is not a long-term catalyst. The market gave the benefit of the doubt to $DDD and $SSYS for quite some time and it bid their prices substantially during most of 2012, but it expected those two to start to deliver in terms of real, organic earnings and sales growth. It did not happen, so some dissapointed market participants just took profits and sold, which put downside pressure on the industry.

There was also a sentiment aspect to the pullback. All of a sudden, in January every local TV and radio were covering 3D-printing and talking about its ginormous potential. Wall Street loves to sell to front page headlines after a substantial move.

In March, both $DDD and $SSYS bounced near their rising 200dmas, where long-term buyers typically step up to support their holdings. Since, then they have been under quiete accumulation. Granted, they still have a lot of work to do in the process of building the right side of their new basis, but the whole sector seems to be setting up again.

From technical perspective, both $DDD and $SSYS had at least a couple of tight consecutive closes and have recently broken their downtrends to the upside. They have been making higher highs and higher lows.

$PRLB has been consolidating after its monstrous earnings gap in February and above $50, it could fly again. It has a small float of only 19M shares, which is a prerequisite for volatile moves.

It is earnings season, so don’t forget to check their earnings dates.

Apple, Cirrus Logic and The Wisdom Of The Market

crus
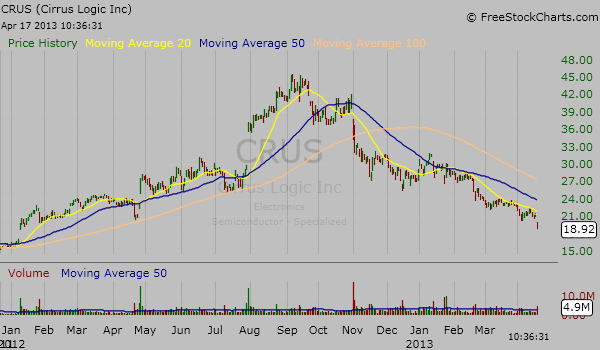
After underperforming for the most part of the past 6 months, Cirrus Logic ($CRUS), which is one of Apple’s suppliers, gapped down again this morning after giving a disappointing guidance. In a about a year, $CRUS went from $19 to $45 back to $19. This is a typical momentum story in a condensed period of time. What are some of the lessons its story reminded of:

1) Once a stock breaks out to new 52-week high from a proper base and on fresh earnings-related catalyst, you don’t know how far the re-pricing could get and for how long the new trend could continue. One of Stanley Druckenmiller’s famous quotes in ‘The New Market Wizards’ book goes something like this:

I never use valuation to time the market. I use liquidity considerations and technical analysis for timing. Valuation only tells me how far the market can go once a catalyst enters the picture to change the market direction.

I wholeheartedly agree with the first part, not so much with the second. I don’t think anyone knows in advance how far a stock could go after it breaks out and any projections are just guesses.

2) Price trends often start and end before earnings trends. When $CRUS destroyed the earnings estimates in November of last year, many people were shocked to see the market reaction – a gap down from $41 to $37. At the time, it was perceived as a buying opportunity by many, citing the spectacular earnings growth. It has been all downhill ever since. The lower the stock went, the more attractive it looked to many, only to be disappointed as surprises often follow the direction of the established trend, until in the end – knowing when that elusive end could be is extremely useful. Poor reaction to what is perceived to be a good earnings report is usually one of the first signs that the price trend is over and since the price is the only thing that pays us, it is the main trend we should pay attention to.

3) Stay away from stocks with low relative strength, especially if they have been recent momentum leaders. In the majority of cases, you will be served better if you stay away from stocks making new 3-month lows (even worse – new 52-week lows) during bull markets. Most of stocks are there for a reason. No matter how appealing the seem from whatever perspective you chose to look at them, you will do yourself a favor not to touch them and go fish somewhere else.