It Is A Very Choppy Environment, But Opportunities Abound For Nimble Traders

The S & P 500 lost 1%, Nasdaq 100 lost 1.5%, small caps shed 0.5% and yet overall there were more stocks that went up 10% for the week (54) than went down 10% for the week (42). It continues to be a market of stocks environment with good opportunities for both bulls and bears, who know how to manage risk. The ST50 list finished the week flat (gained 3 basis points) outperforming the indexes by a good margin.

$SPY tested its rising 50dma for a second time in two weeks. Technicians say that the more one level is tested, the weaker it becomes and the more likely to be taken out. A break below the 50dma is not the end of the world. Many trends test their longer-term moving averages before they resume higher – 100dma, 200dma and even the 50-week MA.

spx

It is a very choppy environment, but opportunities abound for nimble traders who have managed to adjust to the range-bound market environment. Most of the trends last up to 2-3 days before there is a major price reaction. We need to start every day with an open mind and be prepared to see everything.

Three industries stood above the rest last week:
– restaurants: tepid inflation coupled with rising consumer confidence and pure price momentum send stocks $CHUY, $SONC and $RUTH at new multi-year highs. There are a lot more names in the group that are hovering near 52-week highs: $CMG, $TXRH, etc.
– media: the ongoing consolidation in the field is re-pricing the whole TV broadcasting industry. Many of the stocks in the group gained more than 5% last week: $SBGI, $NXST, $SSP, $TVL, etc.
– mortgage investment companies were among the best performers in 2012 and it looks like are returning back to fashion: $OCN, $HLSS, $NSM, $ASPS, etc.

Patterns repeat all the time in financial markets. The only things that change are the names of the symbols involved. Corrections through price and time are a normal stage of any liquidity cycle and they should be embraced as playing a crucial role in the discovery of future leaders. The silver lining of all market corrections is that they highlight the strong stocks with organic demand or real alpha. Pay attention to stocks that make new 52-week highs or gain more than 3% on big down days. For example, during the selloff on Wednesday, one of the very few stocks that made new all-time highs was $CSOD. Then, it proceeded to spike more than 5% near the end of the week.

Most stocks dipped on Friday, when the $SPY struggled just below its already declining 20-day moving average. Here are six St50 members that showed relative strength:
RS June 14

In the book Hedge Fund Market Wizards, one of the featured traders (Jamie Mai) talks about two types of risk – identified and unidentified:

Markets tend to over-discount the uncertainty related to identified risks. Conversely, markets tend to under-discount risks that have not yet been expressly identified. Whenever the market is pointing at something and saying this is a risk to be concerned about, in my experience, most of the time, the risk ends up being not as bad as the market anticipated.

There are two major macro factors that seem to account for the majority of the recent market volatility:
– the re-winding of the Japanese Yen carry trade
– the discounting of potential tapering in the FED’s open market operations

The big question is how much of those risks have already been discounted by the market? They have already been covered extensively by the press, which by no means guarantees their impact will be reduced.

What I wrote about the market on June 6th continues to play out:

There is still plenty of risk appetite for buying dips in select U.S. equities. Today’s bounce does not change the big picture. We are still in a range-bound market environment with elevated volatility – an environment that is known to produce a lot of fake breakouts and breakdowns and be more favorable to mean-reversion setups from important technical levels. This does not mean that the market won’t look strong or weak for 2-3 days in a row. It will look strong or weak long enough to convince most market participants to lay in one direction and then it will swiftly pull the rug under their feet.

With that in mind, there are still plenty of opportunities for nimble traders that manage to quickly adjust to the new market environment and realize that many breakouts and breakdowns are likely to deliver a lot smaller gains than what we got used to in the first 5 months of the year.
Amazon Continues To Take Over The Retail World One Step At A Time

Most companies think about what will change in the next 10 years and position their business according to their projections and expectations. The truth is that no one knows what the next 10 years will look like and what novelties they are going to bring. The globe is moving faster than ever. Product cycles are a lot shorter. So is our attention span. Innovation is travelling faster than the speed of sound. We change our minds and preferences more often. Billion dollar companies are made and ruined within the scope of a decade. It seems that change is the only constant, but is it?

Amazon’s founder and CEO, Jeff Bezos does not believe so. He thinks about what will not change 10 years from now and builds Amazon’s long-term strategy around those constants. Lower prices, great service, faster deliveries and greater product selection – these are cornerstones that are not going to change no matter what. People are not likely to ask to pay more, receive their deliveries slower, have less to choose from and get crappy customer service.

If you stop to innovate, you better close doors and give the money back to your shareholders. This is what corporate America has been doing lately. Not the part about closing doors, but the part about giving back shareholders money through hefty dividends and buybacks. Wal-Mart is the latest example. They announced a new $15 Billion buyback on Friday. Borrowing for share repurchases is the new game in town and almost everyone is playing. Not, Amazon. Yes, they also took advantage of the record low interest rate environment to borrow, but one cannot blame them for lack of ideas where to put their money to work. Amazon continues to innovate and invest in its platform as if it was day one of its journey.

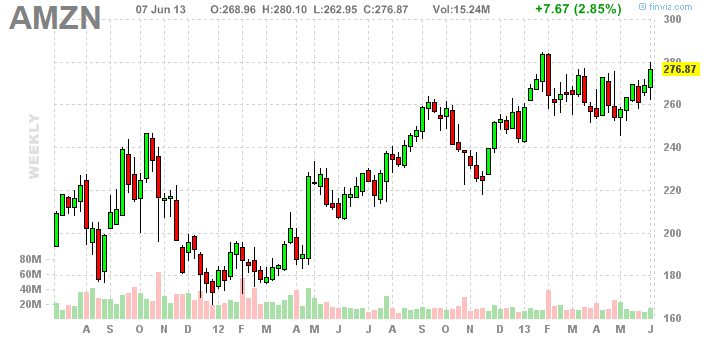
Over the past week alone, Amazon opened its first online store in India, announced that it will sell Kindles in China and expand its nationwide same-day grocery delivery service in the U.S. The market seems to be liking Amazon’s geographic and product expansion. Shares of the online retail giant gained 3% in a volatile week and are trading within very close proximity of their all-time highs of $284.72.

Screen Shot 2013-06-08 at 7.47.52 AM

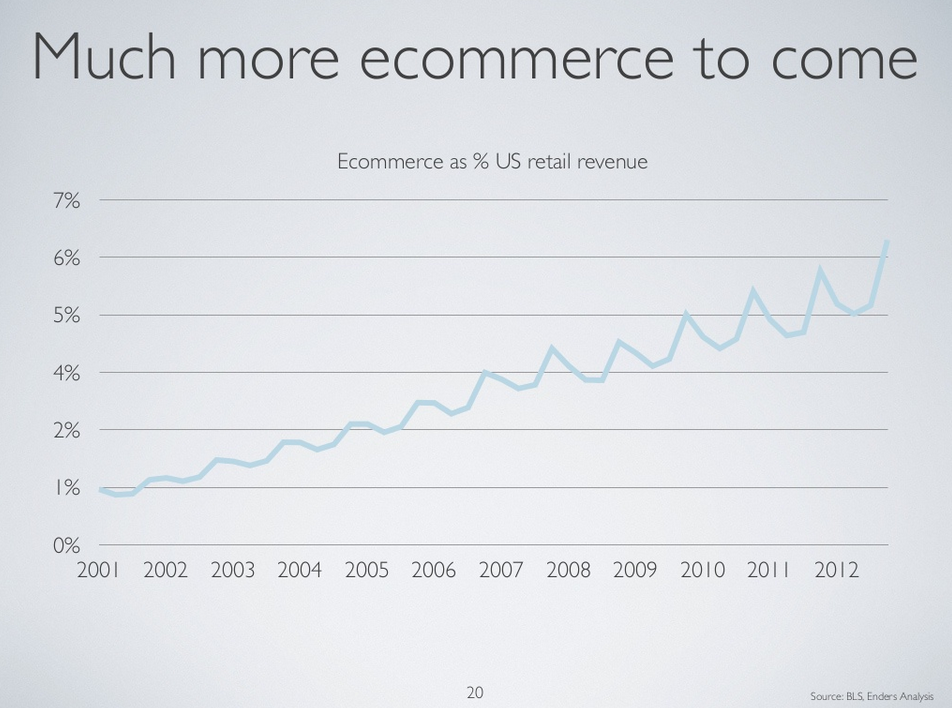
This is not even the big picture of why you might want to consider Amazon as a long-term holding. In 2001, e-commerce accounted for less than 1% of the total retail revenue in the U.S. Today, this number is still only 6.5% in the U.S, which accounts for 5% of the world population. The percentage of online sales is much smaller in the rest of the globe and it is bound to quickly grow in the next decade. If I had to choose one company that is likely to benefit the most from this huge e-commerce trend, it would be Amazon.

Screen Shot 2013-06-08 at 7.49.33 AM

Divergences and Setups Abound

U.S. equity buyers stepped in where they were supposed to step in and after a week of volatility spikes, dip buyers are on the winning side again.

The good news – the recent pullback has helped form quite a few good risk to reward setups. A lot of stocks consolidated side-ways and started to break out near the end of the week when the market averages bounced higher. The St50 list gained 0.93% for the week, outperforming the averages.

The bad news – we are still in a range-bound market, which will continue to deliver a lot of fake breakouts and breakdowns.

Speaking of range-bound and fakeouts, this seems like a good time to talk about the so called “taxi driver syndrome”: people tend to get more active where there is less work to do in order to compensate for the smaller revenue stream and less active when there is a lot of work. In reality, they would do a lot better if they are more active when there is more work to do and just take the day off when there is less work. The same applies to traders and investors. In a higher volatility environment most people naturally make less money, so to compensate, they trade more and try harder for little or even negative results. In clean trending environments is a lot easier to make money, so most people don’t sweat it too much and don’t press to take advantage of the opportunities.

People’s expectations for making equal amount of money every week or month could cause a lot of harm. The return curve in the market has very fat tails – a few stocks and a few months will account for the majority of your annual gains.

Let’s take a quick look at the major asset classes to see where we stand:

major assets

The U.S. Dollar ($UUP) has its worst week in months. The only commodity that benefited from the Dollar’s weakness was crude oil ($USO), which spiked close to 5%. When all is said and done, the “black gold” is still in no man’s land and it doesn’t seem to be going anywhere soon.

The U.S. Dollar and U.S. equities have been going in the same direction for the better part of 2013 and they finally part ways last week. One week does not make a trend, but it is something to watch carefully. Correlations change, but they also tend to continue for years as this chart from Chris Kimble reveals:

dollar:equities

Speaking of divergencies, have you looked at emerging markets ($EEM) lately? They have been underperforming in 2013 and last week broke down to levels not seen since last December, where they sit at major support. The odds are that we might see some type of a bounce there in the coming couple weeks. Despite the weakness in emerging markets, many of the Chinese ADRs are in good shape and had another decent week – $JOBS, $SINA, $BIDU, $CTRP etc.

Interest rates continue to rise as U.S. Treasuries ($TLT) lost ground for a 7th week in a row, dropping to new 52-week lows. Despite the recent spike in yields, they are still near historic lows and financial stocks continue to benefit from the steepening of the yield curve. Among the biggest gainers last week were investment banks, brokers and asset management firms.

Cancel that vacation to Japan. The Yen ($FXY) had a monstrous week and recovered some of its humongous losses since December, but it is still in a downtrend. There are trillions of dollars behind the yen carry trade and the moves there have major implications for all asset classes. Strong Yen is supposed to be negative for equities, but we saw a divergence in that relation near the end of the week.

Take a look at the latest St50 List here.